01
Trusts & Estate Structuring
We establish irrevocable and asset protection trusts that legally shield your assets from creditors, lawsuits, and excessive taxation.
Preserve Your Wealth, Secure Your Future
Your assets represent years of hard work, and without the right legal strategies, they could be at risk from creditors, lawsuits, taxes, or long-term care costs. At Ravenell Law, we help individuals and families safeguard their wealth through proactive asset protection strategies.
Request a Free ConsultationProper planning can protect your assets from unforeseen circumstances while ensuring financial stability for you and your loved ones.
01
We establish irrevocable and asset protection trusts that legally shield your assets from creditors, lawsuits, and excessive taxation.
02
For business owners and investors, we create tailored legal structures, such as LLCs and family-limited partnerships, to safeguard personal assets from business liabilities.
03
Without proper planning, nursing home and long-term care costs can quickly drain your estate. We help you preserve your assets while qualifying for essential benefits.
Asset protection planning in Pennsylvania and New Jersey works inside a set of statutes that decide which transfers hold up, which trusts a creditor can reach, and which accounts are protected. The rules below shape most plans we prepare. This is general information, not legal advice; whether a strategy fits depends on your assets, your family, and any claims that already exist.
Pennsylvania's Uniform Voidable Transactions Act, 12 Pa.C.S. § 5104, lets a creditor void a transfer made with actual intent to hinder, delay or defraud any creditor, whether the creditor's claim arose before or after the transfer. Among the factors a court may weigh are whether the transfer went to an insider, whether the person kept control of the property, whether they had been sued or threatened with suit before the transfer, and whether they became insolvent shortly afterward.
Under 12 Pa.C.S. § 5109, a claim based on actual intent generally must be brought within four years after the transfer, or, if later, within one year after the transfer was or could reasonably have been discovered. This is why asset protection has to be in place before a lawsuit, a business problem, or a care need arises. Moving assets after a claim surfaces often invites a challenge rather than preventing one.
Both states have adopted versions of the Uniform Trust Code, and both follow the same basic rule. During the settlor's lifetime, the property of a revocable trust is subject to claims of the settlor's creditors (20 Pa.C.S. § 7745 in Pennsylvania; N.J.S.A. 3B:31-39 in New Jersey, enacted by P.L. 2015, c. 276). A living trust remains valuable for avoiding probate and planning for incapacity, but it is not an asset protection tool on its own.
For an irrevocable trust, a creditor of the settlor may reach the maximum amount that can be distributed to or for the settlor's benefit. In practice, a trust you create for yourself offers limited protection in Pennsylvania and New Jersey. Irrevocable trusts that benefit a spouse, children, or other family members, and that the settlor cannot draw from, are the structures more often used to protect assets for the next generation.
Federal law already protects many retirement savings. Under ERISA, 29 U.S.C. § 1056(d)(1), each pension plan must provide that benefits under the plan may not be assigned or alienated, which generally keeps employer plans such as 401(k)s out of reach of ordinary creditors.
In bankruptcy, 11 U.S.C. § 522(n) caps the exemption for traditional and Roth IRAs. Effective April 1, 2025, that cap is $1,711,975, not counting amounts rolled over from employer plans and their earnings. Because retirement accounts are already protected to this extent, we review beneficiary designations and account titling before recommending a more complex structure.
Creditors are not the only risk. For transfers made on or after February 8, 2006, federal Medicaid law, 42 U.S.C. § 1396p(c)(1)(B), looks back 60 months from the application for assets given away for less than fair market value. A gift inside that window can delay long-term care coverage, so Medicaid asset planning leaves the most options open when it starts five or more years before care is expected. Our Medicaid and long-term care planning pages explain the Pennsylvania and New Jersey rules in more detail.
Sources
Areas We Serve
Elkins Park, Pennsylvania · New Jersey
Related Resources
Asset protection involves legal strategies to safeguard your wealth from creditors, lawsuits, excessive taxation, and long-term care expenses.
The sooner, the better. Asset protection strategies must be implemented before any legal or financial threats arise to be effective.
Without legal safeguards, your wealth could be exposed to lawsuits, creditors, divorce settlements, or Medicaid spend-down requirements.
Yes. From our Elkins Park, Pennsylvania office, we work with individuals and families in Pennsylvania and New Jersey, including clients who own property in both states. The two states' trust codes treat revocable and self-settled trusts in much the same way, but Medicaid rules, real estate titling, and tax considerations differ, so we plan under the law of the state where each asset is located.
Generally not in Pennsylvania or New Jersey. Under 20 Pa.C.S. § 7745 and N.J.S.A. 3B:31-39, the property of a revocable trust is subject to the settlor's creditors during the settlor's lifetime, and a creditor can reach the maximum amount an irrevocable trust could distribute to the settlor. Trusts for a spouse, children, or other beneficiaries are treated differently, which is why the terms of the trust matter.
It may be too late for some strategies. Pennsylvania law lets a creditor void a transfer made with intent to hinder, delay or defraud a creditor, and a pending or threatened lawsuit is one of the factors a court may consider. Planning can still address exempt assets, retirement accounts, and future risks, but we will not help move assets to avoid an existing claim.
Often, to a large extent. ERISA generally bars assignment or alienation of benefits in employer pension plans such as 401(k)s, and in bankruptcy federal law exempts traditional and Roth IRAs up to $1,711,975 as of April 1, 2025, plus amounts rolled over from employer plans. Protection outside bankruptcy and for inherited accounts can differ, so we review each account's type and beneficiary designations.
Ravenell Law
Ready to discuss asset protection strategies?
Get in Touch
With Ravenell Law, you gain more than legal services—you gain a trusted partner. Let us help you navigate the complexities of estate planning and elder law with solutions tailored to your unique goals.
Visit Us
8033 Old York Road, Ste 210
Elkins Park, PA 19027
Contact Us
(215) 935-6277Hours
Mon – Fri, 9:00am – 6:00pm
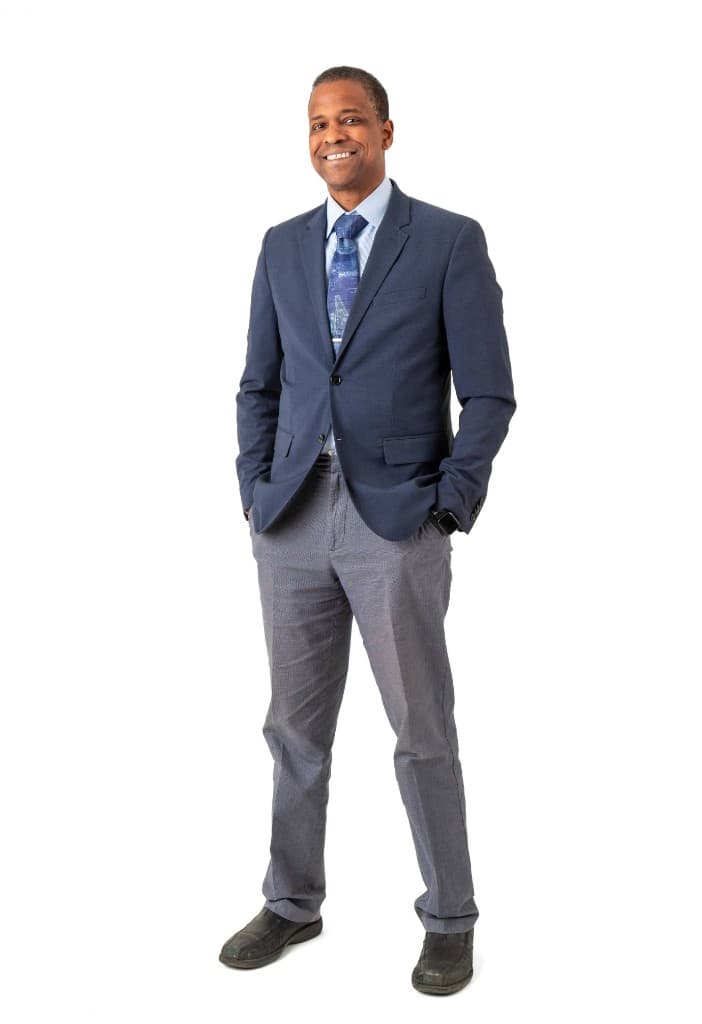
William S. Ravenell
Founder & Lead Attorney
