01
We guide clients through elder care Medicaid planning, helping them retain property and income while qualifying for essential long-term care benefits.
Your Trusted Medicaid Planning Attorney in New Jersey
At Ravenell Law, we help individuals and families throughout New Jersey prepare for long-term care with forward-looking Medicaid planning. Whether you are preparing for the cost of a nursing home or trying to understand how New Jersey delivers long-term care through Medicaid managed care, we work to keep your plan aligned with current law while protecting family assets. We provide legal guidance on durable powers of attorney, estate planning, and asset structuring. Contact our team to begin planning for security, care, and peace of mind.
Many families do not find us years ahead. They find us after a hospital discharge planner says a parent cannot safely go home, and the question becomes how to pay for care this month. That is Medicaid crisis planning, and it uses the same New Jersey rules as advance planning, applied on a shorter clock. This page is general information about New Jersey law, not legal advice about any one application, and no attorney can promise that a particular application will be approved.
Navigating Medicaid regulations in New Jersey requires a careful understanding of eligibility rules, look-back periods, and asset protection mechanisms. At Ravenell Law, we support clients in structuring their finances to comply with Medicaid requirements while ensuring long-term stability for family members and surviving spouses. Whether planning early or responding to an urgent care need, we provide strategic clarity at each step.
New Jersey delivers long-term care Medicaid through Managed Long Term Services and Supports (MLTSS). According to the Division of Medical Assistance and Health Services, an applicant approved both financially and clinically is enrolled in MLTSS and in an NJ FamilyCare managed care organization, and only nursing facility residents who were on custodial Medicaid before July 1, 2014 remain in fee-for-service for the duration of their stay. For a new applicant, the practical question is which managed care plan the nursing home or home-care agency actually participates in, and we help families check that before a placement decision.
New Jersey publishes the numbers that frame most of these conversations. For 2026, the Division lists a gross income standard of $2,982 a month for a person in a Title XIX approved facility, and a penalty divisor of $420.67 a day, effective April 1, 2026, for assets transferred for less than fair market value inside the five-year look-back. When one spouse needs care and the other stays home, the community spouse keeps the greater of $32,532 or one-half of the couple’s total resources, not to exceed $162,660. Effective July 1, 2026, the base monthly maintenance allowance for that spouse is $2,705, and the home equity limit is $1,130,000. These figures change every year, so we check them against the household’s actual statements rather than last year’s chart.
Our firm approaches every Medicaid planning case with precision and compassion. We draft legal documents, including medical powers of attorney and revocable trusts, to support clients through care transitions. Whether you are protecting real estate, retirement accounts, or planning for future incapacity, Ravenell Law offers the experience and insight needed for effective planning.
01
We guide clients through elder care Medicaid planning, helping them retain property and income while qualifying for essential long-term care benefits.
02
We explain how MLTSS and NJ FamilyCare managed care organizations deliver nursing home, assisted living, and in-home care, so families can compare plans with the facility’s network in mind.
03
We integrate estate planning and financial planning with Medicaid eligibility strategies to support aging individuals in protecting their legacies.
04
From drafting durable powers of attorney to handling complex applications, we offer end-to-end legal support that reduces avoidable delay and denial.
Common questions from families in New Jersey.
While estate planning addresses the transfer of assets after death, Medicaid planning focuses on asset protection and eligibility for long-term care benefits during life. Our firm merges both to create cohesive and protective plans.
Federal law sets the look-back at 60 months for transfers made on or after February 8, 2006 (42 U.S.C. § 1396p(c)(1)(B)), so gifts made more than five years before an application are generally outside the review. Starting five or more years before care is expected leaves the most options open and avoids penalties related to asset transfers during the look-back period. It is not too late if care is already needed; see the crisis planning question below.
Crisis planning is Medicaid planning that starts when long-term care is needed now or soon, often after a hospital stay. It works with the assets and income that are there: identifying which assets are countable, documenting past gifts honestly, setting aside the community spouse’s share when one spouse stays home, and filing a complete application. If transfers inside the five-year look-back cannot be explained, New Jersey calculates a penalty period by dividing the value transferred by the penalty divisor, which the State set at $420.67 a day effective April 1, 2026. The State says the penalty clock begins only on the date the applicant is otherwise eligible, but for the penalty, which is why gifts that were never counted are often discovered after the savings are already spent.
A Medicaid lawyer, sometimes called a Medicaid planning attorney, helps an applicant and family qualify for long-term care Medicaid without avoidable delay. In New Jersey that usually means reviewing five years of bank and brokerage statements for transfers, identifying which assets are countable, working out the community spouse’s share and income allowance, preparing or reviewing the application filed with the county social service agency, and coordinating the clinical screening through the county Area Agency on Aging, which is part of the Aging and Disability Resource Connection. It can also mean setting up a qualified income trust when income exceeds the monthly standard, or appealing a denial. The value is in filing correctly and on time, not in any promised result.
For 2026, the Division of Medical Assistance and Health Services lists a gross income standard of $2,982 a month for a person in a Title XIX approved facility, such as a nursing facility. Income above that amount does not end the conversation. Federal law, 42 U.S.C. § 1396p(d)(4)(B), recognizes a trust composed only of pension, Social Security, and other income of the individual, where the State receives what remains at death up to the Medicaid paid. This is commonly called a qualified income trust or Miller trust, and it has to be set up and funded correctly each month.
There are two tracks, and both must be satisfied. Financially, the application for the Aged, Blind and Disabled programs goes to the county social service agency, which reviews income and liquid assets; the State notes that an in-person interview is not required to apply. Clinically, an adult must meet nursing facility level of care, which the State describes as needing hands-on help with three or more activities of daily living, such as bathing, dressing, toileting, transfers, or eating, or having cognitive deficits that require supervision and cueing with three or more of those activities. Adults start the clinical screening through the county Area Agency on Aging and Aging and Disability Resource Connection.
According to the Division of Medical Assistance and Health Services, the spouse who stays at home keeps the greater of $32,532 or one-half of the couple’s total resources, not to exceed $162,660. That spouse may also receive part of the institutionalized spouse’s income: effective July 1, 2026, the base monthly maintenance allowance is $2,705, and shelter costs above $811.50 a month are added to it. The actual figures depend on the couple’s accounts and income when care begins.
Not automatically, but the home is not ignored. New Jersey’s home equity limit for 2026 is $1,130,000. After death, federal law, 42 U.S.C. § 1396p(b)(1)(B), requires the State to seek recovery from the estate of a person who was 55 or older when they received nursing facility or home and community-based services, subject to limits such as a surviving spouse. The statute also exempts certain transfers of the home, including to a spouse, to a child under 21 or a blind or disabled child, or to a son or daughter who lived in the home for at least two years and provided care that kept the parent at home. Which of these apply depends on the deed and who lives in the house, so we review both.
We assist with asset preservation, income planning, durable powers of attorney, and Medicaid application processing. Our approach ensures that clients retain control and clarity while pursuing eligibility.
Long-term care planning often includes advance directives and health care proxies to ensure decisions reflect your wishes even in cases of incapacity. Our firm prepares these critical documents with the appropriate legal authority.
Yes. We provide legal support in resolving disputes, correcting application errors, and appealing denials through the appropriate administrative channels. Many denials come from missing verifications or unexplained transfers rather than true ineligibility, so the first step is reading the notice closely and acting before its deadline.
Serving New Jersey
Ready to talk with Ravenell Law?
Get in Touch
With Ravenell Law, you gain more than legal services—you gain a trusted partner. Let us help you navigate the complexities of estate planning and elder law with solutions tailored to your unique goals.
Visit Us
8033 Old York Road, Ste 210
Elkins Park, PA 19027
Contact Us
(215) 935-6277Hours
Mon – Fri, 9:00am – 6:00pm
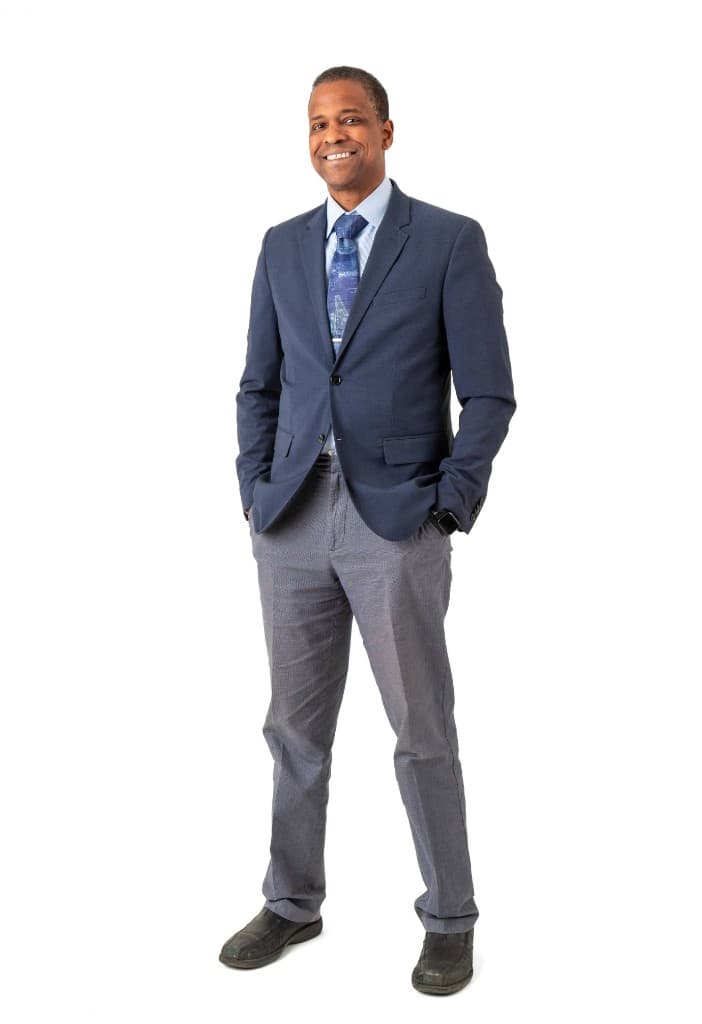
William S. Ravenell
Founder & Lead Attorney